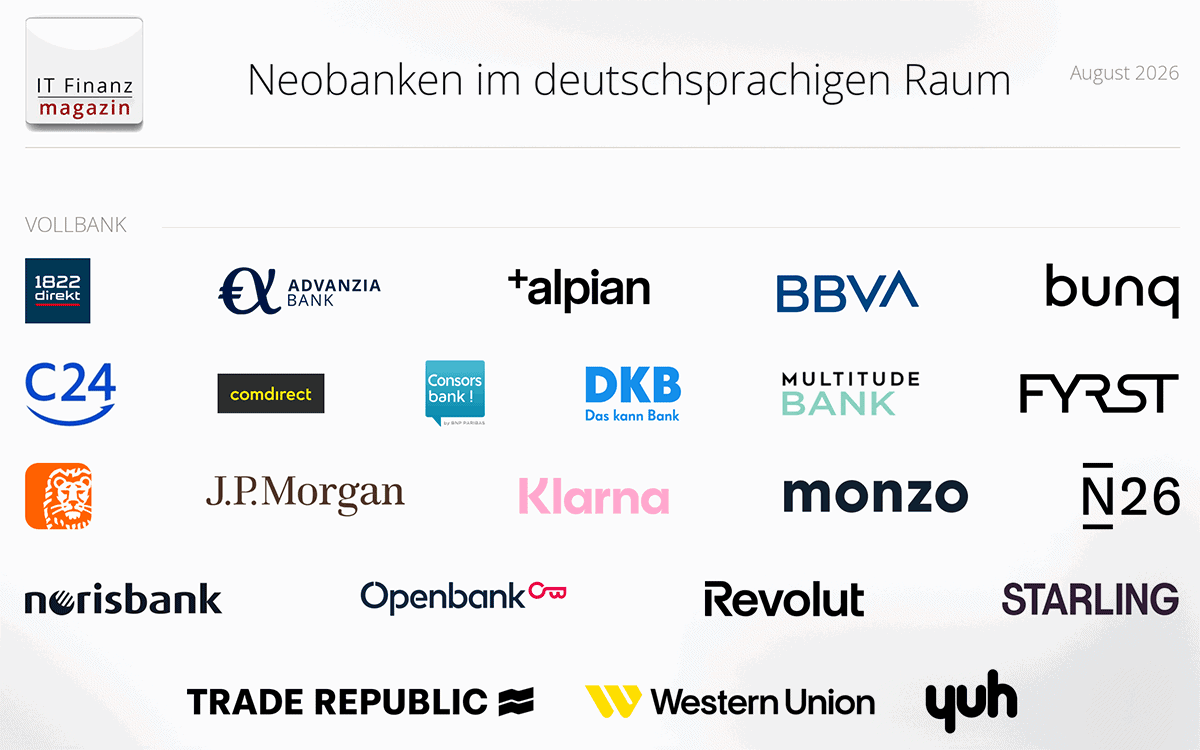
As platforms scale across the Single Market, navigating regulatory licenses—ranging from full banking charters to electronic money institution (EMI) permits—defines how institutions issue International Bank Account Numbers (IBANs) to consumers and businesses.
Full-Bank Charters Versus EMI Licenses in Cross-Border Operations
According to regulatory disclosures, the distinction between a full-service credit institution and an electronic money institution dictates deposit protection schemes and account functionality. Neobanks operating under full banking licenses, such as N26 Bank SE and C24 Bank GmbH, issue German IBANs directly under their own institutional frameworks. Conversely, platforms functioning under EMI directives rely on dedicated partner networks or regional branches to issue local identifiers. For instance, Airwallex (Netherlands) B.V. operates as a Dutch electronic money institution while providing local German IBANs for business accounts, according to corporate disclosures.
Market positioning also varies significantly by target demographic. While legacy direct banks like DKB (Deutsche Kreditbank) maintain millions of retail clients through established parent structures like BayernLB, specialized business platforms target distinct niches. According to corporate data, FYRST operates as a digital brand under Deutsche Bank and Postbank tailored specifically to freelancers and small businesses, mirroring the SME focus of platforms like Qonto and Holvi.
Regulatory Compliance and IBAN Structuring Across Jurisdictions
Account holders frequently encounter multi-jurisdictional frameworks depending on where a fintech holds its primary authorization. Revolut Bank UAB utilizes a specialized banking license issued in Lithuania, allowing it to issue Lithuanian IBANs alongside German IBAN options through its domestic branch network, as detailed in company operational summaries. Similarly, the Spanish financial group Santander operates Openbank under a Spanish banking license, providing customers with Spanish IBAN formats across the European Economic Area.
Payment institutions and specialized platforms further diversify the market by integrating non-traditional assets. Companies like Gnosis Pay and Bitwala bridge fiat payment rails with decentralized finance by offering Visa debit cards linked to stablecoin or crypto wallets, utilizing infrastructure partners such as Monerium and Lightspert Payments Europe AS to process transactions under distinct regional regulatory umbrellas.
Key Takeaways for European Account Holders
- Licensing Directives: Full credit institutions provide direct deposit guarantees up to €100,000 under national statutory schemes, whereas EMI and payment institutions manage client funds through segregated safeguarding accounts with partner banks.
- IBAN Allocation: Local IBAN issuance depends heavily on branch localization; institutions like N26 and C24 issue German IBANs directly, while providers such as Wise and Revolut allocate Belgian or Lithuanian formats based on the issuing corporate entity.
- Target Verticals: Platforms are sharply divided between consumer-facing neo-banks and B2B financial management tools like Qonto, Holvi, and Pliant, which integrate corporate expense tracking with standard digital ledger services.
Frequently Asked Questions
What is the difference between a neobank with a banking license and an EMI?
According to regulatory definitions, a full-bank license allows an institution to extend credit and hold deposits protected by statutory deposit guarantee schemes up to €100,000. Electronic Money Institutions (EMIs) cannot traditionally grant loans from customer deposits and must safeguard client funds in dedicated accounts held with commercial partner banks.
Why do some digital banks issue foreign IBANs to domestic users?
Fintechs often leverage the European Union’s passporting rights, allowing an entity licensed in one member state—such as Lithuania, France, or Spain—to offer services across the entire bloc. However, consumer demand for local IBANs has prompted many cross-border providers to establish domestic branch offices to issue local account identifiers.